FOR BUSINESS OWNERS
You've built the business.
Why does the money still feel unclear?
Most owners I talk to have the pieces - a CPA, a retirement plan, investments, insurance. What they don't have is one system making those pieces work together. I call that the money fog. This free one-page infographic shows a strategy some owners use to clear it: the Family Bank Strategy - parking business surplus in high cash value whole life insurance and borrowing against it on their own schedule, instead of a bank's.
What the infographic walks you through:
The Family Bank Strategy, step by step, on one page - no 40-page ebook, no jargon wall
Why surplus cash sitting in a business checking account is quietly doing nothing for you
How policy loans work in plain terms - borrowing against cash value for a hire, equipment, or property, and repaying on your schedule
The trade-offs, spelled out honestly: loan interest, reduced cash value while a loan is outstanding, and what happens if a policy isn't managed properly
How the strategy sits alongside the team you already have - your CPA, your investments, your existing coverage
Send me the infographic
No spam, no selling your information. One email with the infographic, then a couple of follow-ups. Unsubscribe anytime.
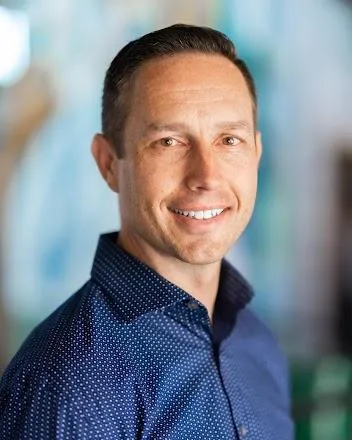
Wade Reed
I help business owners turn a pile of financial pieces into one clear system. For 15 years I've worked with owners across the country — over Zoom, not in a branch office — evaluating the whole picture first, then deciding what each dollar's job is. The Family Bank Strategy is one tool in that work. It fits some owners well and others not at all, and I'll tell you plainly which one you are. I also host the Wealth Acceleration Podcast.
This page and the infographic are educational information only — not financial, tax, or legal advice. The Family Bank Strategy involves high cash value whole life insurance; whether it fits your situation depends on your finances, health, and goals, and it isn't right for everyone. Policy loans accrue interest and reduce cash value and the death benefit; unpaid loans can cause a policy to lapse, which may have tax consequences. Dividends are not guaranteed. Any potential tax advantages depend on current tax law and your individual circumstances — talk to your CPA or tax advisor before acting on any of this.